This week, the market tests the tension between ambitious expansion and sheer capital discipline. Whether it is silicon infrastructure, premium consumer goods, or heavy marine engineering, investors are pulling the microscope away from top-line revenue and pointing it directly at the balance sheet. Scouter's ranked setups for the week highlight three names where forward guidance and unit economics will dictate the immediate repricing.
Navigating the AI Capex Burden at Baidu
First up on Monday, November 16, 2026, Baidu (BIDU) faces a critical Q3 2026 earnings release that resolves by Saturday, November 21, 2026. The search giant is caught in a transitional squeeze, forced to pivot hard into AI-native marketing and cloud infrastructure as legacy advertising revenues decline. Building out data centers and training models requires heavy capital expenditure, and the market is closely scrutinizing whether that capital intensity can deliver real returns.
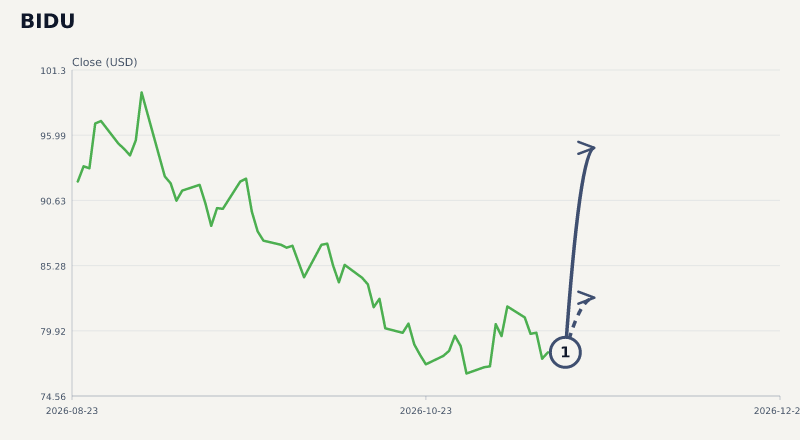
The print will test Baidu's ability to maintain its cloud growth trajectory without letting infrastructure costs crush operating margins. Scouter’s analysis models a bullish target of $94.95 against a bear floor of $82.64, tracking a 72% probability that strong cloud execution offsets capex drag. If management can demonstrate that its AI investments are translating into sustainable margin expansion rather than just structural overhead, the stock has room to run from its recent $78.15 close.
Margin Stabilization at Amer Sports
The microscope shifts to Consumer Discretionary on Tuesday, November 17, 2026, when Amer Sports reports Q3 earnings. Following a recent bearish print that triggered alarms over margin compression, the apparel holding company needs to prove it can protect pricing power. It is no longer enough to just sell more Arc'teryx jackets; the street demands proof that the cost to acquire and serve those customers is not deteriorating.

For Amer Sports, the headline revenue figure is a sideshow to the forward guidance reset. Scouter models a $33.37 target if management can convincingly guide toward stabilized margins, measuring a 74% probability for a bullish resolution by November 29. If inventory bloat or promotional discounting creeps into the commentary, the name risks testing its $30.22 bear floor as the market re-rates the stock on mix rather than trailing sales.
Monetizing the FLNG Conversion Cycle
Rounding out the week on Wednesday, November 18, 2026, Golar LNG delivers its Q3 results. The marine infrastructure player operates in a notoriously capital-intensive environment, where heavy conversion capex for floating liquefied natural gas (FLNG) vessels can easily cannibalize free cash flow. After a neutral earnings report last quarter that still drove the stock higher on 20-year charter monetizations, the focus now pivots to the pure sustainability of that cash flow generation.
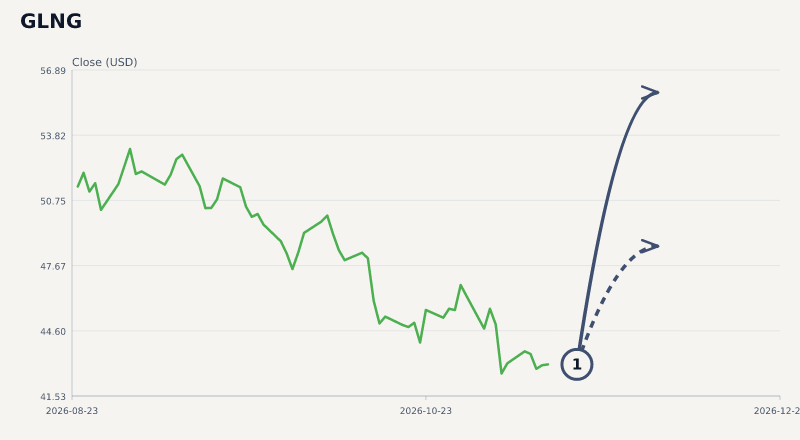
The Energy setup hinges entirely on project execution guidance. Scouter's catalyst modeling points to a $55.83 target against a $48.59 bear floor, heavily weighted by how global LNG demand trends influence Golar's long-term charter visibility. If leadership can validate their cost discipline while executing on heavy conversion projects, the name is positioned to capture its modeled expected return profile as the catalyst resolves into early December.
The Universal Demand for Unit Economics
Whether a company is deploying capital into silicon, synthetic fabrics, or marine steel, the leniency for growth at any cost has evaporated. This week’s catalyst slate underscores a market that refuses to underwrite visionary expansion without a clear, near-term bridge to free cash flow.
The setups across Baidu, Amer Sports, and Golar LNG all hinge on the exact same mechanism: management's ability to defend their margins while absorbing transitional costs. When the dust settles on these prints, the winners will be the ones that treated their balance sheets as carefully as their product pipelines.