The era of scaling unmonetized users ended a few quarters ago, but the market is still punishing technology platforms that missed the memo. This week, the spotlight shifts to three distinct Information Technology players navigating the tricky transition from audience growth to hard unit economics. Whether deploying generative AI tools or pruning legacy content costs, the mandate across the sector is identical: prove the margins actually scale.
Bilibili and the Content Cost Reality Check
First up is **BILI**, which reports Q3 results on Tuesday, November 24, 2026. The Chinese video platform slid toward 52-week lows heading into the print, pressured by mobile gaming declines and rising short-drama ad competition. The upcoming release serves as a structural test of management's ability to protect expanding margins without cannibalizing user engagement.
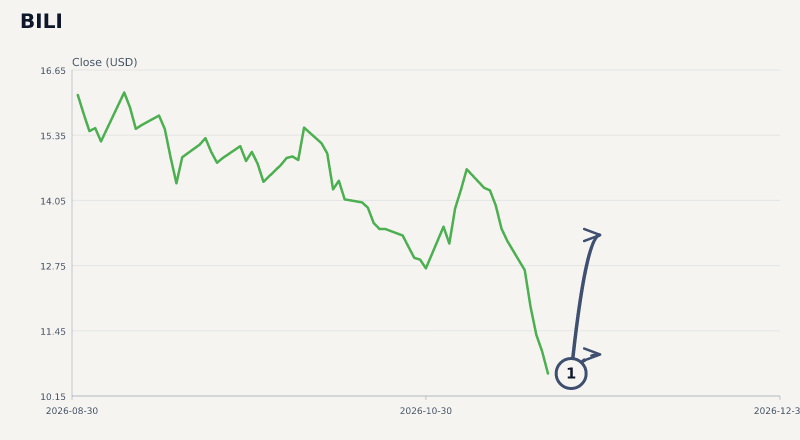
Scouter's scenario work models a 75% probability of a bullish resolution by the end of the week, with an expected move pushing toward a $13.36 target. Validating that bull case requires a definitive reset in forward guidance, specifically proving that content costs have peaked. If advertising growth decelerates under competitive pressure, the setup models a bear floor retracement to $10.98.
Opera’s Aria AI Monetization Hurdle
Browser developer OPRA faces a similar profitability test when it reports on Tuesday, November 24, 2026. Following a mixed second-quarter showing, the market needs concrete evidence that Opera's integrated browser AI, Aria, is actively driving revenue. Eyeballs alone no longer command a premium multiple if the ad tech fails to convert.
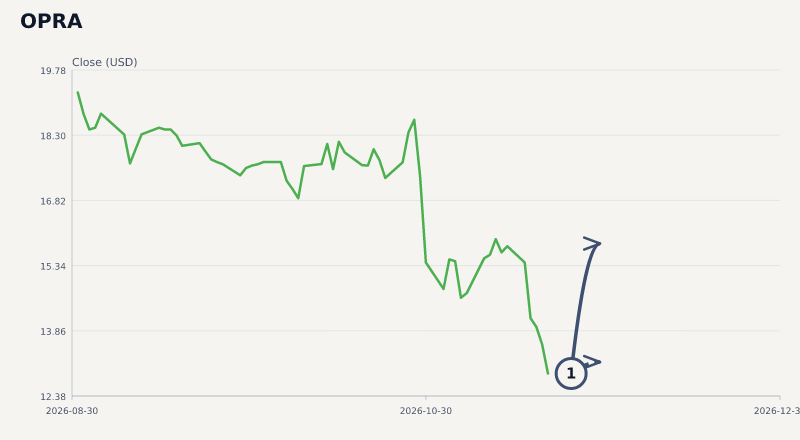
The modeled range frames a setup where investors are hunting for structural margin expansion rather than just top-line beats. Scouter models a $15.84 upside target on a favorable print, assuming management delivers clean guidance on AI monetization. The bear floor sits at $13.15, leaving little room for error if ad conversions slip during the quarter.
Brand Engagement Network’s Enterprise Pivot
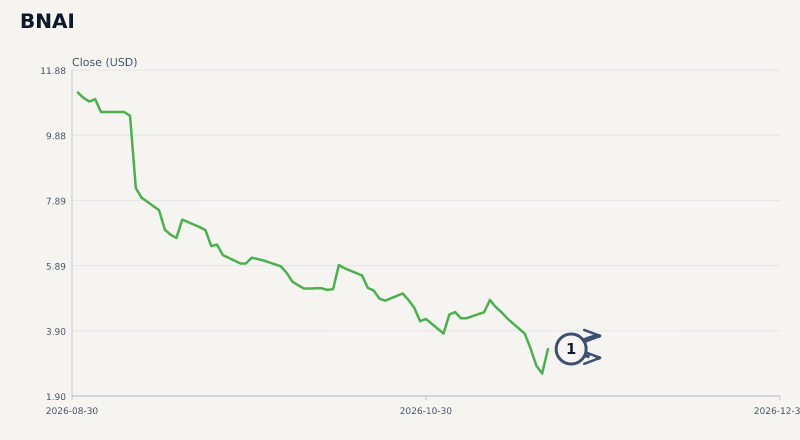
At the micro-cap end of the spectrum, enterprise AI software provider BNAI reports Q3 earnings on Tuesday, November 24, 2026. The stock recently absorbed a sharp macro-driven bearish hit as investors dumped high-burn, low-revenue SaaS names across the board. The company has previously delivered positive earnings surprises, but the market is heavily discounting those beats against broader liquidity concerns.
To reverse the downward drift, Brand Engagement Network needs to issue confident margin commentary and map a clear path to enterprise software deployment. Scouter maps a $3.74 bull target if the guidance reassures investors on cash runway and contract momentum. A failure to soothe those macro sensitivities tests a tight bear floor at $3.07.
The Unit Economics Mandate
The throughline for all three setups is a market aggressively filtering for capital discipline. Investors are no longer willing to fund perpetual technology science projects or limitless user acquisition campaigns. The platforms that survive this tightening cycle are the ones translating engagement into durable free cash flow.